
The latest on Energetic and renewable energy trends.
How Lenders Underwrite C&I Solar Portfolios With Mixed Credit Quality

A commercial and industrial (C&I) solar portfolio can include customers with very different credit profiles, from investment-grade companies to smaller businesses without a credit rating. For lenders, that means looking beyond how much power the projects will produce to assess whether customers can keep paying under their contracts over the life of the loan.
That mix of credit quality can make financing more complicated. Lenders need to understand exposure by counterparty and what protection is available if a customer stops paying. At Energetic Capital, we provide credit insurance that helps developers and owners address those concerns and bring more lenders into the conversation.
What Lenders Look For
When underwriting these portfolios, lenders assess both the individual customers and the portfolio as a whole. Who is responsible for paying under each power purchase agreement (PPA)? How much revenue comes from the largest customers? If one defaults, how would that affect the portfolio’s ability to repay its debt?
An unrated customer is not necessarily a poor credit risk, but assessing its financial strength takes more work. Lenders need enough information to get comfortable with that exposure and a structure that accounts for the risks they identify.
Why Mixed-Credit Portfolios Can Be Financeable
Not every customer needs an investment-grade rating for a portfolio to secure financing. Lenders may get comfortable with a mix of credits when:
- Revenue is spread across customers, industries, and locations, limiting dependence on any one source.
- Reserves, parent guarantees, or credit insurance provide support if a customer cannot pay.
- The portfolio can withstand some customer defaults and still meet its debt obligations.
- The sponsor has the experience and resources to monitor customers, manage payment issues, and respond to defaults.
What Lenders Evaluate in Mixed-Credit C&I Solar Portfolios
Lenders look at each customer’s ability to pay, how much the portfolio depends on that customer, and what happens if payments stop. Those questions shape how much debt the portfolio can support and the protections a lender may require.
Customer credit and concentration
The starting point is the company responsible for paying under each PPA. For unrated customers, financial statements, payment history, and any parent guarantees help lenders assess financial strength beyond the absence of a credit rating.
The size of each exposure matters, too. A weaker customer representing a small share of revenue raises different concerns than one accounting for a quarter of the portfolio. Lenders also look for shared risks across customers. A portfolio with many separate offtakers may still be heavily exposed to one industry or local economy.
Contracts and continued access to the site
A long-term PPA provides a basis for financing, but lenders also need to understand what happens if the customer sells the property, vacates the building, or closes its business. Can the contract transfer to a new customer? Can the project owner continue accessing and operating the system and does that market allow ability to [virtual] net meter? What rights does the lender have to step in and address a default?
These provisions affect the options available when something goes wrong. Clear site rights, assignment provisions, and cure periods can help preserve a project’s value, although they do not guarantee a replacement customer or uninterrupted revenue.
Cash flow under stress
Lenders test whether the portfolio can service its debt when results fall short of expectations. Alongside lower solar production, downside cases may include late payments, customer defaults, and time needed to replace lost revenue. The combination matters: losing a major customer during a period of weaker production can put more pressure on cash flow than either event alone.
Those results help determine loan size and the required debt service coverage ratio (DSCR). Greater uncertainty may lead a lender to size debt more conservatively or require additional support.
Reserves and credit support
Reserves give a portfolio cash to draw on during payment interruptions. Depending on the transaction, lenders may also require cash to be retained when performance deteriorates, rather than distributed to the owner.
Parent guarantees and credit insurance can provide additional protection against customer nonpayment. Lenders assess who stands behind that support, what it covers, and when funds would be available. The structure needs to account for both potential losses and the cash needed to keep servicing debt while a payment issue is resolved.
The sponsor’s ability to manage the portfolio
Lenders want to know who will monitor customer financial health, follow up on overdue invoices, maintain the projects, and respond to defaults. A sponsor’s experience handling those issues is relevant alongside its development and operating track record.
A useful financing package brings this information together: customer financials, revenue concentrations, key contract terms, downside cash flows, and proposed credit support. It should give lenders a clear view of where the risks sit and how the sponsor plans to manage them.
How Energetic Capital Helps Address Offtaker Credit Risk
A developer can have well-built projects and signed PPAs, yet still struggle to secure financing because lenders are uncomfortable with the customers behind those contracts. That can mean less debt, more cash tied up in reserves, or fewer lenders willing to consider the portfolio.
At Energetic Capital, we provide credit insurance that protects against covered offtaker payment defaults. By placing that protection with highly rated insurers, we give lenders an additional source of repayment if a customer fails to meet its obligations. Coverage is structured around the underlying revenue contracts and financing requirements, with defined limits, terms, and conditions.
For developers and owners, that can expand financing options, support greater debt proceeds, and reduce reliance on cash collateral or other credit support. It can also give them more flexibility to include unrated or below-investment-grade customers in a portfolio. The financing benefit depends on the transaction, the coverage provided, and how the lender recognizes that protection.
How Credit Insurance Fits Alongside Other Protections
Lenders often use a combination of tools to address customer payment risk. A parent guarantee adds support from a stronger company, while a letter of credit provides bank-backed payment security but uses the customer’s banking capacity. Cash reserves provide liquidity during interruptions, and assignment provisions can help preserve options if a customer leaves the site or sells the business.
Credit insurance can supplement these protections and, where lenders agree, replace some guarantee or collateral requirements. The aim is to address the credit exposure in a way that supports financing while leaving developers and customers with more capital available for their businesses.
Preparing Your Portfolio for Financing
Before approaching lenders, put together a clear picture of who pays, how much each customer contributes, and what support sits behind those obligations. A useful starting point is a customer schedule showing financial information, contract terms, revenue exposure, and any guarantees or other credit support. Identify concentrations early so they can be addressed before they become a sticking point in financing discussions.
Build downside cases alongside the base case. Show what happens if a major customer stops paying, how long reserves would last, and what assumptions you have made about recovering or replacing that revenue. Be clear about who will monitor customer credit, manage collections, and respond when payments fall behind.
If credit insurance is part of the proposed structure, bring the insurance provider into the discussion while financing terms are still being developed. That gives the sponsor, lender, and insurer time to assess which exposures can be covered and how the coverage would fit with the loan requirements.
At Energetic Capital, we work with sponsors and lenders through that process, from reviewing the customer mix to structuring coverage around the financing. Starting early helps establish where insurance can make a meaningful difference to debt proceeds, collateral requirements, or lender participation.
Frequently Asked Questions
What is a mixed-credit C&I solar portfolio?
It is a group of commercial and industrial solar projects whose customers have different credit profiles. Some may be investment-grade companies, while others are lower-rated or unrated businesses. Being unrated does not necessarily mean a customer is financially weak, but lenders need to assess its ability to meet long-term payment obligations.
How does customer credit affect how much debt a portfolio can support?
Lenders assess how much contracted revenue they are comfortable relying on to repay the loan. Concerns about customer credit or concentration can lead to lower debt proceeds, higher coverage requirements, or additional reserves. Guarantees, credit insurance, and other protections may help lenders give more value to revenue they would otherwise discount.
What does credit insurance cover?
Credit insurance protects against covered payment defaults under the insured contracts, subject to the policy’s terms and limits. It gives lenders and project owners financial protection if an insured customer fails to pay. It does not cover every reason a project might lose revenue, such as equipment failure or lower solar production.
How does credit insurance compare with other forms of credit support?
Each tool addresses risk differently. Parent guarantees depend on the guarantor’s financial strength, letters of credit provide bank-backed support, and reserves put cash aside for payment interruptions. Credit insurance transfers defined payment default risk to an insurer and can work alongside these tools or replace certain requirements where the lender agrees.
When should a developer consider credit insurance?
It is worth exploring when customer credit is limiting debt proceeds, narrowing the lender pool, or creating significant collateral requirements. Bringing it into discussions early gives the parties time to assess coverage and determine whether it improves the financing.
Does Energetic Capital compete with lenders?
No. We provide credit insurance that supports financing from banks and other capital providers. We work with sponsors and lenders to address offtaker credit concerns that could otherwise limit a transaction.
Bringing the Portfolio to Lenders
A mix of customer credit profiles does not have to prevent a C&I solar portfolio from securing financing. Sponsors can make the process easier by presenting clear customer information, realistic downside cases, and a plan for managing payment disruptions.
If offtaker credit is a sticking point in your financing, Energetic Capital can help assess whether credit insurance would address the lender’s concerns and support the terms you are seeking.
Financing Renewable Energy Projects With an Unrated Offtaker
A renewable energy project can have a strong site, proven technology, and an experienced development team and still struggle to secure financing. Sometimes, the sticking point is the customer buying the power.
When that customer, or offtaker, doesn’t have a public credit rating, lenders have more work to do. They need to understand whether the buyer can meet its payment obligations over the life of the contract and what happens to the project’s cash flow if it can’t.
An unrated offtaker isn’t necessarily a weak customer. Many established private businesses, municipalities, and cooperatives operate without a rating from S&P, Moody’s, or Fitch. But without that outside assessment, lenders need other ways to get comfortable with the risk.
For developers and sponsors, addressing that uncertainty early can make a meaningful difference in whether a project gets financed and on what terms.
Why the Buyer’s Credit Matters
Lenders rely on a project’s expected cash flow to support debt repayment. A long-term power purchase agreement (PPA), energy service agreement, lease, or tolling agreement helps establish that revenue stream. Its value to a lender, however, depends in part on the buyer’s ability to keep paying.
With an unrated offtaker, lenders typically take a closer look at:
- The customer’s financial health and ability to meet long-term obligations.
- The contract’s payment terms and protections.
- The project’s options to monetization if the agreement is terminated.
- The time and revenue needed to replace a customer.
That additional uncertainty can translate into less debt (if available at all), higher borrowing costs, larger reserves, or a greater equity contribution from the sponsor. Some lenders may require a guarantee or other credit support before moving forward.
The project’s technical strengths still matter. But they don’t resolve the separate question of who pays if the customer defaults.
Making the Contract Easier to Finance
The best time to address offtaker credit risk is while the project and its contracts are still taking shape.
Start with the PPA/offtake agreement itself. Clear payment obligations, pricing, default provisions, cure periods, termination rights, and lender protections give financing partners a better basis for evaluating the revenue.
Financial modeling should then test what happens when those revenues come under pressure. What if the customer stops paying? What if the contract terminates early? How much replacement revenue would the project need, and how quickly?
Working through those questions helps identify the specific risks that need support. Depending on the transaction, that support might include a parent guarantee, a letter of credit, cash reserves, or credit insurance.
Where Credit Insurance Fits
Credit insurance can help bridge the gap between an unrated customer and a lender’s credit requirements by transferring covered payment-default risk to an insurer.
At Energetic Capital, we work with developers, sponsors, and financing partners to structure credit insurance and risk-transfer solutions for renewable energy projects. The aim is to give lenders greater confidence in contracted revenue and help projects access capital that might otherwise be difficult to secure.
Depending on the coverage and the lender’s requirements, that support can help:
- Broaden the pool of potential lenders.
- Improve borrowing terms.
- Reduce the need for additional sponsor support.
The outcome depends on the transaction, including the policy’s terms, coverage limits, exclusions, and the insurer’s credit quality.
These solutions can support a range of technologies and contract structures, including solar, wind, storage, fuel cells, and energy efficiency projects.
Planning for Portfolios
The same credit questions arise when financing a portfolio of smaller projects. Spreading revenue across multiple customers can reduce dependence on any one buyer. Still, lenders need to understand the portfolio’s overall credit quality, customer concentrations, and contract terms. A larger number of contracts doesn’t automatically resolve those concerns.
A coordinated approach to credit support can help sponsors address them across the portfolio. For example, Energetic Capital helped facilitate a $225 million credit facility for a distributed generation portfolio backed by private equity. Embedding credit insurance helped improve terms and allowed the facility to accommodate twice as much non-investment-grade exposure. For developers adding projects over time, establishing that financing approach early can also make it easier to plan future growth.
Bring Credit Into the Conversation Early
Waiting until the final stages of financing to address an unrated offtaker can lead to revised terms, additional documentation, and delays. A more effective approach is to evaluate the customer’s credit during contract negotiations, identify what lenders will need, and build the appropriate support into the transaction. That gives developers, insurers, and financing partners time to align the contract, coverage, and debt structure.
An unrated offtaker doesn’t have to prevent a good renewable energy project from moving forward. With clear contracts and credit support suited to the transaction, developers can give lenders a stronger basis for financing it.
If offtaker credit is holding up your project, connect with Energetic Capital to explore the options.
Energetic's Summer Reading List
This marks the third summer we are sharing our team's summer reading list; it is always one of our best performing posts.
You can check out last year's collection of our favorite summer reads. Encourage everyone to see if they can find these in their local independent bookstore.
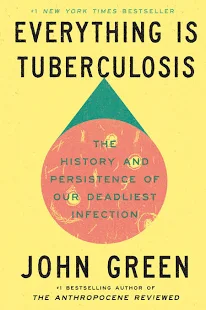
Nathan: Everything Is Tuberculosis: The History and Persistence of Our Deadliest Infection. There is a saying I like to repeat as often as possible: "much was decided before we were born." I am a sucker for non-fiction that spans generations to get insight into why the world is the way it is. I think there are often useful insights we can apply in our day-to-day. Our routines are shaped by decisions made long ago by people we never met. Mapping these themes across history is a helpful reminder of how little we control, but also the strategies at our disposal to control what we can
Vinny: Dilla Time: The Life and Afterlife of J Dilla, the Hip-Hop Producer Who Reinvented Rhythm. I’m a big hip-hop fan, and J Dilla’s influence on the genre is undeniable. His creativity and unconventional approach to rhythm, micro-chopping, and his signature swing have always fascinated me, so I’m excited to finally read a book that’s been on my list for a while. Fun fact: Dilla's MPC 3000 is in the Smithsonian's National Museum of African American History in DC.
Heath: The Martian. When reading for pleasure, I’m a big fan of anything science fiction. After having read other works by Andy Weir, I’ve enjoyed the consistent theme of how logical problem-solving, engineering, and scientific thinking can overcome even the most difficult challenges. I also appreciate the message that resilience, perseverance, optimism, and creativity are often the keys to succeeding when circumstances seem impossible. I think these are compelling themes that extend beyond space exploration and reflect the challenges we encounter in everyday life.
Sawyer: The Last Great Game - Duke vs. Kentucky. I grew up in Kentucky (where Duke is public enemy #1) and always heard stories of the game when Laettner hit the shot of all shots to beat Kentucky. I never knew the backstory of how each team got to that point, what was going on in the minds of these players and coaches, and how important this game was to the history of college basketball. Every year in March... Kentucky fans are forced to relive this moment and getting to hear about what went on behind the scenes is very cool!
Peter: Dune. This Frank Herbert classic is a study in the art of influencing others through words and actions. What is not said is often more important than what is said, and we should always measure our words based on what we want our audience to think. Dune offers a masterclass in this. My boss recommended this book to me mentioning one of his favorite quotes: "If only he had the sublty to match his courage, he would be quite formidable."
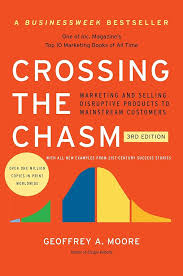
Steve: Crossing the Chasm. One of the biggest challenges in building great products isn't writing the code, it's getting people to actually use what you've built. The gap between early enthusiasts and the much larger audience that only adopts a product when it's intuitive, reliable, and clearly solves an important problem. That transition isn't just a marketing challenge. It begins with product design. It requires understanding how users think, what they value, and where friction prevents adoption.
How Lenders Think About Concentration Risk in Renewable Energy Portfolios
Portfolio managers overseeing renewable energy loan portfolios are acutely focused on concentration risk, their potential exposure to losses due to over-reliance on a limited number of counterparties, sectors, or geographies. In practical terms, when a bank or fund reviews a renewable project or portfolio, one of their primary questions is not just, “Is this project financeable?” They ask, “How does this exposure interact with every other loan or contract we already have?” This core question drives lender behavior and, ultimately, determines project finance outcomes for developers, sponsors, and asset owners.
At Energetic Capital, we see first-hand how proactive management of concentration risk opens new doors, structuring transactions that unlock capital for renewable projects serving even unrated or sub-investment-grade offtakers. Understanding the technical side of lender risk frameworks, and the solutions available for mitigation, is essential to scaling renewables and attracting broad-based investment.
Defining Concentration Risk in Renewable Energy Lending
Concentration risk in lending refers to the risk that a lender faces outsized losses due to a portfolio’s lack of diversification. If too much lending is tied to a particular borrower, sector, or geographic region, a single adverse event can trigger unexpectedly large losses. For renewable energy, these concentrations often revolve around:
- Single name exposure (for example, many loans to the same corporate offtaker)
- Sector concentration (for example, a high proportion of exposure to community solar, distributed generation, or a single clean energy technology)
- Geographic concentration (for example, assets clustered in one ISO or state)
- Product/structure uniformity (such as all non-recourse, long-tenor project loans)
These concentrated exposures can behave unpredictably in market downturns, regulatory shifts, or following credit events; quickly overwhelming traditional risk models that assume diversified portfolios. In a renewable context, portfolio managers and credit committees use internal frameworks to actively track, measure, and govern these concentrations.
Why Lender Concentration Risk Drives Financing Outcomes
Lenders assign significant weight to concentration risk because concentrated portfolios are more susceptible to tail events, rare but severe losses. In renewable lending, the presence of high concentration often leads to:
- Stricter advance rates on project or portfolio debt
- Increased pricing or fees for new transactions
- Shorter tenors and amortization requirements
- Outright rejections based on internal limits (“We like the asset, but we are full on this client or offtaker”)
Many platforms find that even highly attractive projects stall because internal lender allocations have already been met for a given offtaker, market, or sector. Lenders must also adhere to regulatory guidelines and reporting standards, which require clear demonstration of diversified, well-controlled portfolios; directly influencing their willingness and capacity to fund additional deals.
How Lenders Measure and Manage Concentration in Renewable Portfolios
Most institutional lenders embed concentration controls within a formal risk framework. This framework typically incorporates:
- Explicit exposure limits for individual offtakers, corporate groups, sectors, and geographies
- Risk rating systems that differentiate counterparties more granularly by creditworthiness, contract structure, and asset type
- Portfolio-level metrics like scenario analytics and stress testing against correlated defaults
- Ongoing monitoring and reporting with early warning indicators for rating migration, sector shocks, or regulatory/policy changes
At the practical level, lenders will compare each new exposure against their internal allocations. If a renewable platform proposes a 15 MW portfolio all contracted to a single national retailer, already at the bank’s maximum allowed exposure, lender flexibility will be severely limited, regardless of project-level economics or technical merit.
Unique Concentration Patterns in Renewable Energy
Renewable energy portfolios often display concentration patterns that differ from traditional lending books. Four drivers stand out:
- Recurring offtakers: Platforms frequently aggregate many projects under repeat relationships with a small number of corporate buyers through PPAs or ESAs. This appears as a single-name exposure in lender risk models.
- Sector verticalization: Specialized developers (for instance, those focusing on logistics, data centers, or municipal customers) may have a majority of revenue tied to a narrow segment.
- Geographic clustering: Favorable incentives, interconnection capacity, or regulatory support cause projects to cluster within certain ISOs, states, or utility footprints.
- Structural homogeneity: Renewable debt is overwhelmingly long-dated, non-recourse, and reliant on similar contracted revenue structures, making portfolios sensitive to correlated performance risk.
Lenders recognize these dynamics and treat renewable portfolios as uniquely prone to event risk, especially as penetration grows and new asset types (such as storage or hybrid projects) are introduced.
Real-World Manifestations of Concentration Risk
For many developers and asset owners, the challenge of concentration risk becomes tangible in interactions with lenders when:
- They receive feedback that further lending to a specific offtaker, sector, or market is not possible without an exception or risk mitigation
- Term sheets come back with increased pricing or tighter covenants to compensate for portfolio concentration
- Portfolio expansions require breaking up transactions, syndicating smaller tranches, or delaying execution due to internal credit committee constraints
As a developer or capital allocator, understanding these patterns is critical to managing deal certainty and to scaling programmatic financing.
How Credit Insurance and Risk Transfer Reshape Concentration Risk
Mitigating concentration risk is a central focus for both lenders and sponsors. Among the solutions available, credit insurance stands out for its ability to transfer risk and directly address internal portfolio restrictions.
The Role of Credit Insurance in Renewable Portfolios
Energetic Capital specializes in credit insurance and risk transfer solutions that serve precisely this need. When integrated at the contract level (for instance, to cover PPA or ESA payment defaults), credit insurance enables:
- Transformation of unrated or sub-investment-grade counterparty exposure into investment-grade equivalent risk
- Lower internal concentration loadings for lenders
- Smoother syndication and broader lender participation, even in portfolios with concentrated offtaker or market exposure
Credit insurance provided by Energetic Capital is tailored for renewable and clean energy infrastructure (including solar, storage, wind, fuel cells, and community solar), and is structured specifically to align with project finance requirements and capital markets standards.
Evidence from Real Transactions
The impact of credit insurance is visible in several documented cases:
- A distributed generation platform with non-investment-grade customers used credit insurance to unlock a $225 million credit facility, double non-IG exposure, speed up closings, and reduce diligence costs.
- An energy efficiency-as-a-service (EaaS) developer extended financing eligibility, deployed $50 million, reduced their cost of capital by 30%, and achieved 15% annual portfolio growth, all by making more customer contracts acceptable to lenders through credit enhancement.
- A wind project supporting over 40 MW of new capacity secured $20 million in permanent debt by insuring P99 revenue exposure with Energetic Capital’s solutions.
These examples underscore how risk transfer not only solves lender concentration constraints but also delivers direct economic benefits; improving terms, attracting new capital, and enabling continued growth even as portfolios become more clustered in specific sectors or with strategic offtakers.
Best Practices for Managing Concentration Risk in Renewable Portfolios
- Take a portfolio-first view: Anticipate how lenders see risk across all exposures, not just for a single project
- Be transparent about potential concentrations and bring proactive solutions to the table
- Use credit insurance and other risk transfer strategies intentionally, designed to fit the specific pressure points of your lenders
- Work collaboratively with credit officers and risk committees, not just originators, to set up scalable, repeatable financing programs
- Standardize key documentation to ease replication and accelerate capital deployment
How Energetic Capital Empowers Borrowers and Lenders
Because credit risk, not project performance or technology, is a primary constraint on liquidity for many renewable portfolios, credit insurance unlocks new capital pathways. Energetic Capital operates exclusively as a neutral partner, de-risking transactions and expanding capital access. Our demonstrated ability to facilitate over $1.5 billion in project value, support wider lender syndication, and deliver repeatable, scalable solutions makes us the industry’s go-to expert for tackling concentration risk.
FAQ: Concentration Risk in Renewable Energy Portfolios
What is concentration risk and why does it matter in renewable lending?
Concentration risk is the potential for outsized portfolio losses when lending is too heavily focused on specific names, sectors, or geographies. In renewables, this can occur if a lender has many loans to the same offtaker, or large exposure to one platform, region, or asset type. It matters because it increases susceptibility to tail events and often leads to tighter credit controls, higher pricing, or outright rejections for otherwise viable projects.
How do lenders formally manage concentration risk?
Lenders use internal frameworks that set explicit limits by obligor, sector, and geography. They monitor exposures using analytics like the HHI index, scenario stress tests, and regular reporting of shifts in credit profile or sector conditions. Portfolio management and risk officers are responsible for oversight and adherence to these frameworks.
What tools are available to mitigate concentration risk?
Common mitigation tools include credit insurance, risk transfer to third-party insurers, selling or participating loans, adjusting underwriting standards, and in some cases holding additional capital against concentrated exposures. Credit insurance is especially valuable in the renewable sector for converting unrated exposures into investment grade equivalents and broadening lender participation.
How does credit insurance help developers and asset owners facing lender concentration constraints?
Credit insurance enables developers and asset owners to structure transactions that are more acceptable to lenders by protecting against payment default on long-term contracts. This makes portfolios eligible for more debt and better financing terms, particularly when offtaker or regional concentrations would otherwise trigger lender limits.
Conclusion
Lender concentration risk is a defining factor in renewable project finance. For sponsors, developers, and investors seeking reliable, scalable access to capital, proactively addressing concentration risk is no longer optional, it is fundamental. Credibly quantifying and mitigating concentration is what moves the needle in lender credit committees and opens the door to expanded, repeatable financing.
For tailored advice on integrating credit insurance to unlock capital and overcome lender concentration constraints, reach out to Energetic Capital. Our award-winning risk transfer solutions are purpose-built for the evolving needs of renewable energy finance.
What Drives Credit Insurance Pricing in Renewable Project Finance: Premium Levers, Data, and Deal Structure
Credit insurance is now a foundational component of renewable energy project finance, especially as capital providers contend with the credit risks inherent to long-term power and energy service contracts. At Energetic Capital, we specialize in quantifying and transferring these risks, making clean energy assets financeable for a broad universe of developers, financiers, and investors. To fully understand what drives credit insurance pricing in renewable project finance, it’s crucial to break down the levers that influence premiums, the data driving risk assessment, and how deal structure directly shapes insurance outcomes.
What Determines Credit Insurance Premiums for Renewable Energy Projects?
Credit insurance premiums are governed by a blend of project- and counterparty-specific factors, advanced analytics, and real-time market dynamics. In practical terms, the most significant premium determinants are:
- Counterparty Risk: The creditworthiness of the offtaker or counterparty under the revenue contract is the largest variable in premium setting. Unrated or sub-investment-grade (sub-IG) entities typically attract much higher premiums than established investment-grade (IG) offtakers.
- Contract Terms: The duration and structure of revenue contracts (such as Power Purchase Agreements, Energy Service Agreements, or leases) impact expected risk over time. Longer contracts, or those with more expansive coverage needs, result in higher cumulative exposure and thus higher premiums.
- Coverage Scope & Limit: The portion of project cashflows insured, whether 80% or just a first-loss layer, has a direct and often non-linear relationship to cost.
- Historical Performance & Data: Actual, observed loss rates, sector-specific data, and insights from large portfolios all drive risk assessment. For renewable energy, a track record of low default frequency can materially reduce pricing.
- Market Conditions: Macro trends such as shifts in reinsurance costs or evolving risk appetites among insurers indirectly shape premiums through broader pricing cycles.
Definition: Credit Insurance in Renewable Project Finance
Credit insurance in the context of renewable project finance is a risk transfer mechanism designed to protect lenders, investors, and asset owners from losses due to nonpayment by an offtaker or contracted counterparty. At Energetic Capital, this insurance is custom-built for clean energy projects, whether solar, wind, battery storage, fuel cells, or community energy assets. Policies are structured to cover defaults under core project contracts, unlocking capital, enhancing lender terms, and often making otherwise challenging projects financeable.
The Core Levers That Drive Credit Insurance Pricing
- Counterparty Credit Quality: Premiums for unrated or sub-IG offtakers can be two to three times greater than for IG offtakers assuming all other things being equal.
- Contract Term & Coverage Period: Each year of added exposure increases the premium cost compared to a shorter tenor, due to compounding default probability. Structures that allow the insurance exposure to step down quickly can generate substantial savings.
- Insured Limit & Scope of Coverage: Insuring 90-95% of contracted cashflows costs more than insuring only an initial loss layer.
- Diversification: For sponsors aggregating projects, bundling diversified portfolios can lead to significant premium discounts.
- Macro & Market Reinsurance Factors: External market forces, such as increases in the cost or capacity of reinsurance, can indirectly add to premiums during volatile periods.
How Data and Analytics Inform Credit Insurance Pricing
At Energetic Capital, we have built a proprietary analytical platform to evaluate credit risk using data from more than 1,800 operating clean energy sites across the US. Our approach uses:
- Probability of Default (PD) Curves: Drawn from industry-standard sources and real-world portfolio data.
- Loss Given Default (LGD): Evaluated based on the project structure, presence of guarantees, local eletricity markets and recovery potential for the underlying obligation through other mitigants available to the project(s).
- Exposure at Default (EAD): Determined from revenue contract terms and the scale of project cash flows.
- Stress Testing and Scenarios: Portfolio performance through volatile cycles, including analogs to historical market disruptions, is tested to assess resilience.
This data-driven underwriting enables project sponsors to obtain highly tailored, competitive premium rates and enables capital providers to reliably price risk.
Real Case Studies: How Credit Insurance Reshapes Renewable Finance
- PE-backed Distributed Generation Portfolio: Energetic Capital enabled a $225M credit facility spanning combined heat and power, storage, electric vehicle infrastructure, and rooftop solar contracted with non-investment-grade customers. Insurance coverage improved debt terms, doubled allowable concentration of non-IG offtakers, and reduced the cost and timeline of diligence.
- Energy Efficiency-as-a-Service Developer: By leveraging Energetic Capital’s analytics and risk transfer, a portfolio unlocked $50M in new deployment, reduced capital costs by 30%, achieved 15% annual portfolio growth, and streamlined due diligence on otherwise challenging customer contracts.
- Wind Project Solution: For a 40MW wind project with an unrated offtaker, Energetic Capital’s policy covered up to P99 revenue, which allowed the project to secure $20M in permanent debt and deliver renewable electricity addition to the regional grid.
- Fuel Cell System Deployment: Coverage for a behind-the-meter fuel cell system enabled project closure with sub-IG counterparties, delivering energy savings and job support in less than three months.
Best Practices for Project Sponsors and Capital Providers
- Engage Early: The earlier in the development and financing life cycle credit insurance is considered, the wider the range of options and the greater the ability to optimize terms.
- Emphasize Data Quality: Transparent, complete, and up-to-date financials and contract documentation are vital. Robust data accelerates underwriting and delivers sharper premium quotes.
- Seek Portfolio Solutions: Group similar projects, especially across non-IG offtakers, to maximize diversification credits and improve pricing.
- Lean on Specialist Partners: Work with dedicated platforms such as Energetic Capital whose track record and focus on renewable credit risk support better execution, capital access, and competitive coverage options at scale.
FAQ: Credit Insurance Pricing in Renewable Project Finance
What is the typical range of credit insurance premiums for renewable projects?
Most projects price annual credit insurance between 2.5% to 7% of the insured limit, with the largest cost driver being the counterparty’s credit quality, insured tenor, and coverage structure.
When should project sponsors consider credit insurance?
Credit insurance should be evaluated as early as possible during project development, negotiations with lenders, or when non-investment-grade offtakers are involved. Early assessment gives sponsors more leverage to optimize structure and terms.
How does portfolio structuring affect the price?
Aggregating projects with different offtakers (especially with varying credit grades) improves risk diversification, which can lead to significantly lower insurance premiums than single-asset transactions.
Why do lenders and investors require credit insurance in renewables?
Lenders require predictable, investment-grade risk profiles to fund projects at scale. Insurance reduces risk, expands lender participation, and brings investment-grade execution to projects with unrated or weaker counterparties.
What distinguishes Energetic Capital in this market?
Energetic Capital focuses solely on credit risk solutions for renewable projects, has enabled over $800 million in value, and supports a range of technologies. Our data-driven approach, proprietary analytics, and S&P A- insurance partnerships deliver flexible, bankable solutions at scale.
Conclusion
Ultimately, credit insurance pricing in renewable project finance is a product of deep risk assessment, structured deal architecture, and tailored data analytics. Sponsors that understand and actively manage each lever: counterparty quality, contract structuring, coverage sizing, and transparent data; are best positioned to unlock bankability and scale project deployment. At Energetic Capital, we partner with forward-thinking developers, lenders, and portfolio managers to deliver certainty and liquidity where it matters most: at the intersection of credit risk and project financing.
If you’re ready to see how your project, portfolio, or transaction could benefit from credit insurance, reach out to our team for a confidential, data-driven assessment and a premium quote tailored to your unique structure.
Community Solar Financing: Managing Subscriber Risk and Improving Bankability
In community solar financing, lenders face a unique challenge: the stability of cash flows depends directly on subscriber payments rather than a single creditworthy offtaker. Banks and institutional investors must assess the risk of payment shortfalls due to consumer churn or an anchor default. This underpins both eligibility for debt and the ultimate cost of capital. When underwriting flags unsatisfactory subscriber risk, solutions to mitigate that risk, such as credit insurance, become critical, enabling even portfolios with non-investment-grade or unrated anchors or residential subscribers to become financeable.
At Energetic Capital, we have seen first-hand how intentional risk transfer allows projects to overcome this primary constraint on financing. Our expert-driven approach to credit insurance and risk quantification expands debt access, unlocks more cost-effective terms, and turns what was a blocking issue into a strategic advantage for sponsors, lenders, and project owners alike.
What Is Subscriber Payment Risk in Community Solar?
Community solar projects operate on a subscription model. Often times hundreds of residential, commercial, and small business subscribers purchase a share of the electricity generated, with revenues distributed based on each participant's usage. This structure creates a highly diversified revenue base but introduces complexity: financial performance hinges on the payment reliability of a large, dynamic customer base rather than a single utility or investment-grade corporate offtaker.
The core risk, known as churn, is the prospect that a portion of subscribers willterminate their subscription, or exit the program abruptly. This risk impacts the project’s ability to meet debt service, directly influencing the willingness of lenders to participate, the terms they offer, and the required reserve or enhancement strategies.
How Lenders Underwrite Subscriber Payment Risk
Lenders and investors apply a detailed, multi-layered framework to assess subscriber risk in community solar projects. Their process resembles traditional counterparty credit analysis but is adapted for scale and nuance. At Energetic Capital, we routinely advise teams on optimizing for these criteria.
Step-by-Step Underwriting Overview
- Portfolio Credit Quality: Lenders analyze aggregate FICO scores, payment histories, and, for business subscribers, audited financials.
- Subscription & Churn Management: They expect 80–100% subscription at closing and active plans for quickly substituting any non-paying or departing subscribers, modeling churn rates and substitution speed (often under 30 days).
- Diversification: Strong portfolios minimize concentration risk by limiting exposure to any one geography, customer segment, or sector.
- Subscription Manager Track Record: Experienced operators with a history of maintaining high subscription levels and minimizing churn are more trusted. Lenders scrutinize the admin’s billing, collections, and customer management capabilities.
- Cash Flow Stress Testing: Projects are modeled for payment default scenarios and must be able to meet minimum Debt Service Coverage Ratios (DSCR) even under adverse conditions.
- Documentation and Utility Billing: Robust, standardized contracts and strong utility on-bill repayment mechanisms enhance reliability. Non-standard documentation can increase diligence costs and risk.
- Portfolio Size: Lenders typically require projects or portfolios of sufficient scale ($15M+ in capacity) for institutional financing.
What Triggers Underwriting Failure?
Underwriting may fail, meaning the project cannot obtain institutional-grade debt, when the subscriber pool does not meet the Lender's thresholds. Typical failure points include:
- Too large a share of subscribers below underwriting thresholds or heavy reliance on unrated C&I customers
- High geographic or sector concentration
- Lack of a robust churn and subscriber management process
- Poorly-documented contracts, insufficient operational experience, or unclear cash collection mechanisms
What to Do When Underwriting Fails: Strategic Response Framework
If a community solar project cannot achieve lender-required risk thresholds, there are several proven strategies to solve or mitigate the issue:
- Bundle Project Types: Combine community solar with stronger credit assets, such as contracted rooftop or utility-scale solar, to diversify and "lift" the overall credit profile.
- Subscription Management Guarantees: Some Subscription managers will offer "churn guarantees" for the projects which they manage. Part of the challenge here is often these Subscription Management companies are often unrated themselves and thus lender's may not provide full credit to such guarantee.
- Transfer Risk via Credit Insurance: Work with a specialist platform like Energetic Capital to obtain bespoke credit insurance, which can convert non-investment-grade exposures to investment-grade equivalents. Our EneRate Credit Cover has enabled portfolios to double non-investment grade concentration and achieve up to 30% lower capital costs by issuing an insurance Policy by an A- (S&P) rated insurer.
- Target Mission-Aligned Lenders: In some instances, approaching lenders with a specific mandate for community or impact financing may yield more flexibility.
Energetic Capital has led successful risk transfer initiatives at every stage: from small distributed portfolios to major term loan facilities, consistently resulting in broader lender participation, improved terms, and faster closings throughout the clean energy transition.
Case Studies: Credit Insurance in Action
- Distributed Generation Portfolio: Energetic Capital’s insurance enabled a $225M credit facility for a PE-backed developer serving non-investment-grade customers. Lender appetite doubled for these riskier counterparties, diligence costs dropped, and deal flow accelerated.
- C&I Portfolio: In another example, EneRate Credit Cover supported an $80M term loan for a distributed generation owner, unlocking efficient capital while banks increased limit allocations.
- Wind Project: By ensuring up to P99 revenue with insurance, Energetic Capital facilitated $20M in debt to a 40MW wind asset with an unrated offtaker, advancing project schedules and improving grid resiliency.
- Energy Efficiency and Fuel Cells: Our credit solutions extended contract eligibility, reduced developer cost of capital by 30%, and fueled rapid portfolio growth in complex, diverse asset settings.
Best Practices for Managing Subscriber Payment Risk
- Quantify Portfolio Risk Early: Use advanced analytics or partner with credit insurance experts to model default, churn, and concentration risks upfront before seeking lender commitments.
- Invest in Subscriber Management: Demonstrate robust customer acquisition, billing, and replacement processes. Lenders reward operational maturity with better pricing and flexibility.
- Standardize Contracts and Billing: Wherever possible, employ standardized subscription agreements and leverage utility on-bill collection to reduce payment friction and limit step-in triggers.
- Aggregate for Scale: Consider structuring deals as diversified portfolios to reach the scale where institutional lenders and insurers can deploy capital efficiently. This reduces per-project diligence costs and reserve requirements.
- Partner Proactively on Risk Transfer: Integrate credit insurance at the structuring stage. Early engagement with experts like Energetic Capital positions projects for the broadest lender participation, avoids surprises at closing, and unlocks optimal terms.
Why Credit Insurance is Transformational for Community Solar
Credit insurance turns subscriber payment risk from a roadblock into a structuring lever. By removing the threat of payment default from the capital stack, risk transfer enables developers to achieve investment-grade risk profiles even with non-investment-grade subscribers, eliminating the need for costly reserves, parent guarantees, or overcollateralization. The result is better terms, greater leverage, extended tenors, and a wider universe of participating lenders.
Our clients consistently report:
- Access to larger debt facilities for previously unbankable portfolios
- More predictable and accelerated closings
- Smoother diligence with less gating friction
- Improved sponsor economics by retaining flexibility in deal structure
Energetic Capital stands alone as a dedicated partner to the renewable finance industry, offering advanced underwriting and risk quantification alongside practical insurance solutions. We are singularly focused on the credit bottlenecks that shape the clean energy asset finance landscape.
Frequently Asked Questions
How does credit insurance work for community solar?
Credit insurance shifts the risk of subscriber payment default from the lender or project sponsor to a highly rated insurance counterparty. If subscribers fail to pay, the insurance policy makes the Insured whole for covered losses, enabling greater confidence and access to bank or bond finance, sometimes at meaningfully improved rates and terms.
What are the typical requirements for lenders to finance a community solar portfolio?
Lenders require demonstration of high subscription rates (ideally 95%+ at close), proven ability to quickly substitute churned subscribers, diversified revenue streams, mature billing and collections, clear contractual structures, and, increasingly, a credit enhancement such as insurance when the commercial subscriber base is unrated or non-investment-grade.
When should I consider credit insurance in my financing process?
It is best to engage with a credit insurance partner early, as this allows you to structure deals for maximal lender acceptance and avoid last-minute surprises or sudden shifts in debt economics. Early integration, before finalizing lender lists, often yields the greatest leverage in negotiations.
How does Energetic Capital support community solar finance?
Energetic Capital specializes in renewable energy credit risk, bringing advanced analytics, deep market knowledge, and award-winning credit insurance products to bear on every challenge. We partner with developers, sponsors, and capital providers to unlock new projects and accelerate closings, supporting over $1.5B in project deployment nationwide.
Conclusion
Subscriber payment risk is a defining challenge of community solar finance, but it need not be a permanent barrier to closing bankable debt. With careful modeling, proactive management, and the integration of proven tools like credit insurance, both sponsors and financiers can achieve their goals in a rapidly evolving market. Energetic Capital is proud to lead this transition for the clean energy sector.
If you’d like to discuss solutions tailored to your specific project or portfolio needs, connect with us to see how our approach to credit enhancement can unlock the full value of your clean energy pipeline.